

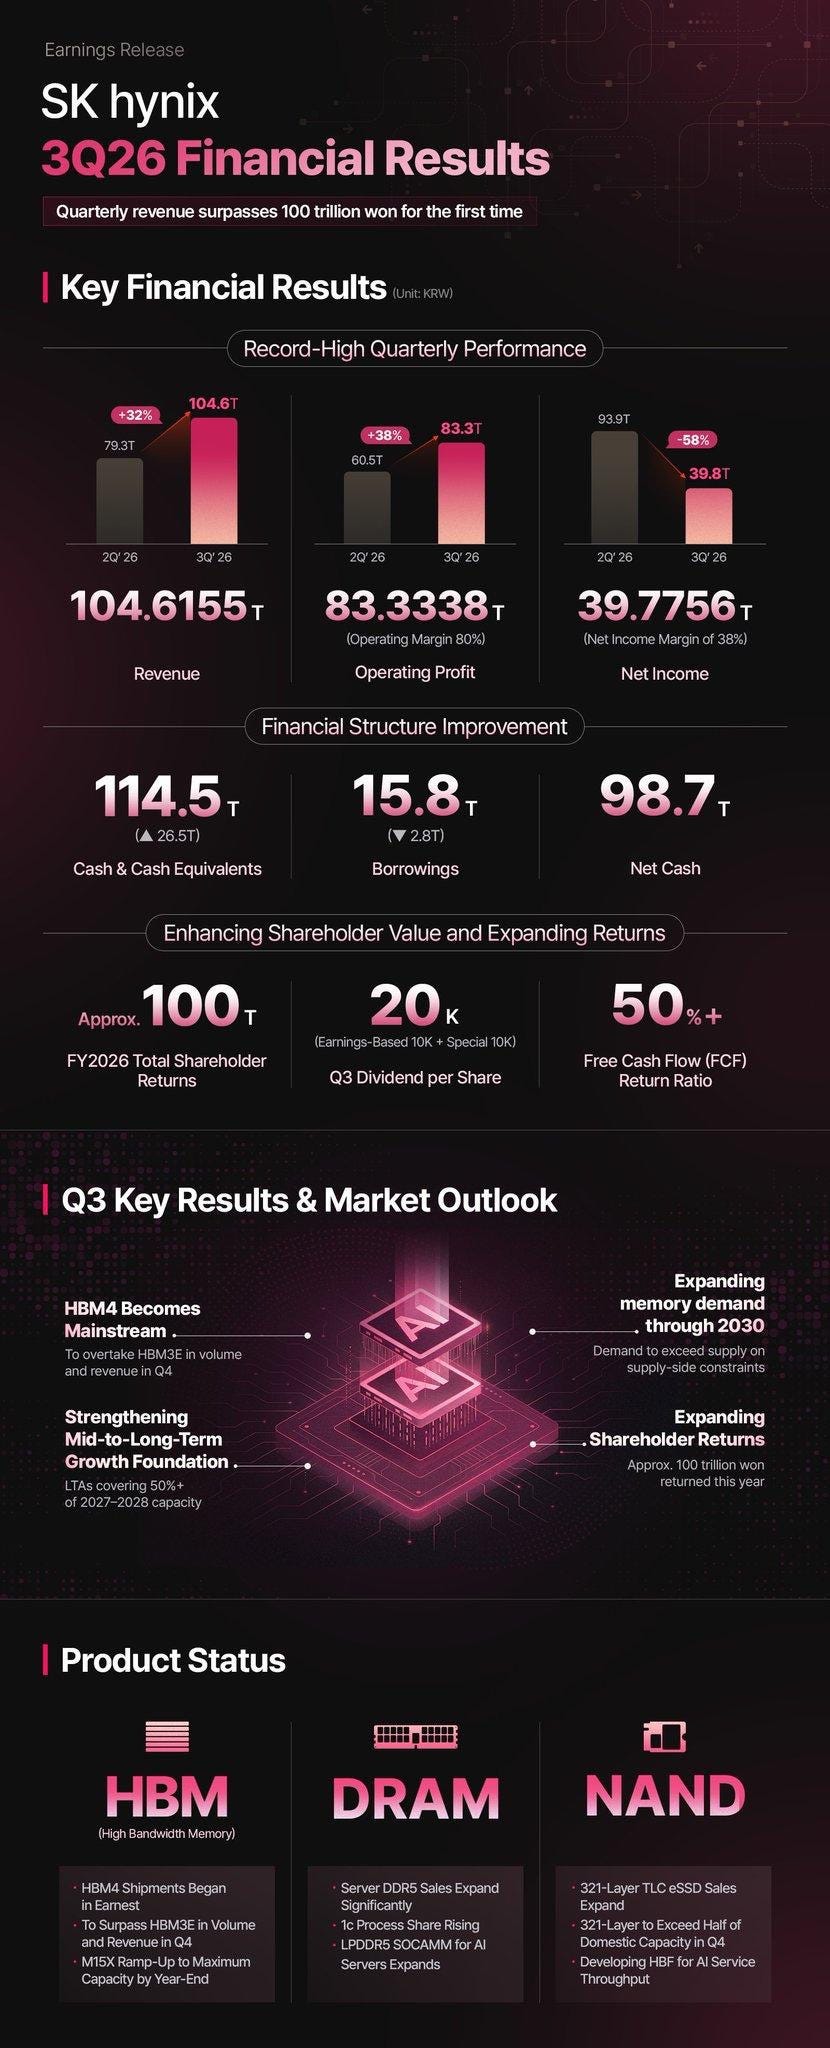
SK Hynix just reported results, and they were nothing short of extraordinary.
Q3 operating profit of $63B, beating consensus by 8%.
Management said DRAM and HBM are effectively sold out through 2029, with demand expected to exceed supply through 2030.
2027 HBM prices have already been agreed upon with its main customers, with every forecast I’ve seen pointing to increases of 65% to 159%.
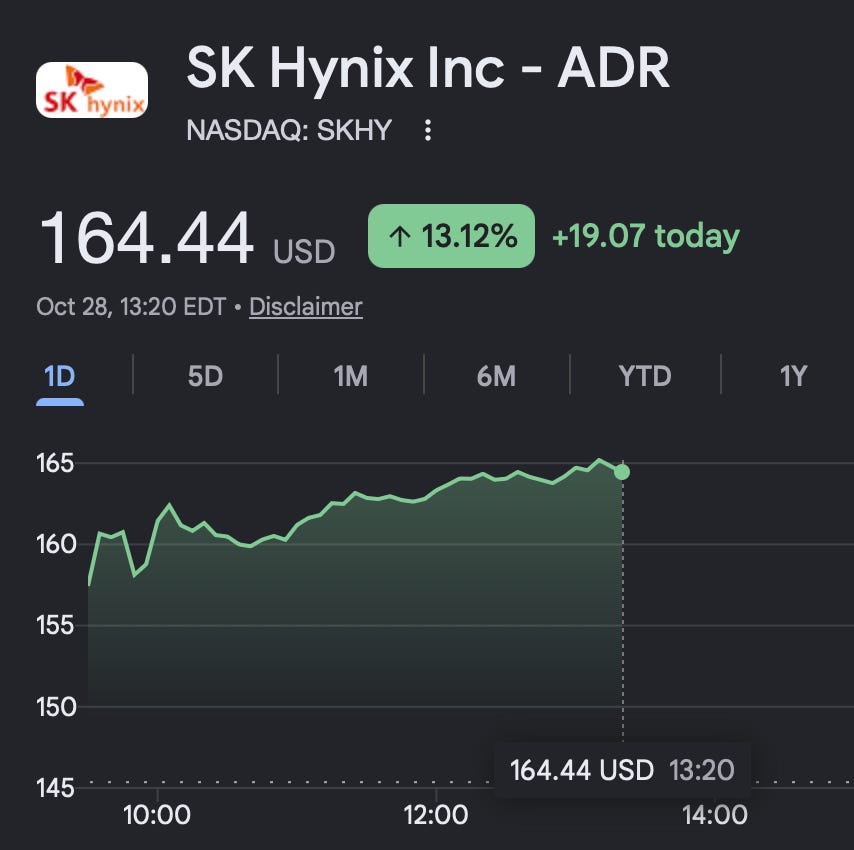
The stock is up 13% on the news.
However, with record earnings and share prices still considerably below their all-time highs, there’s one question we need to ask ourselves.
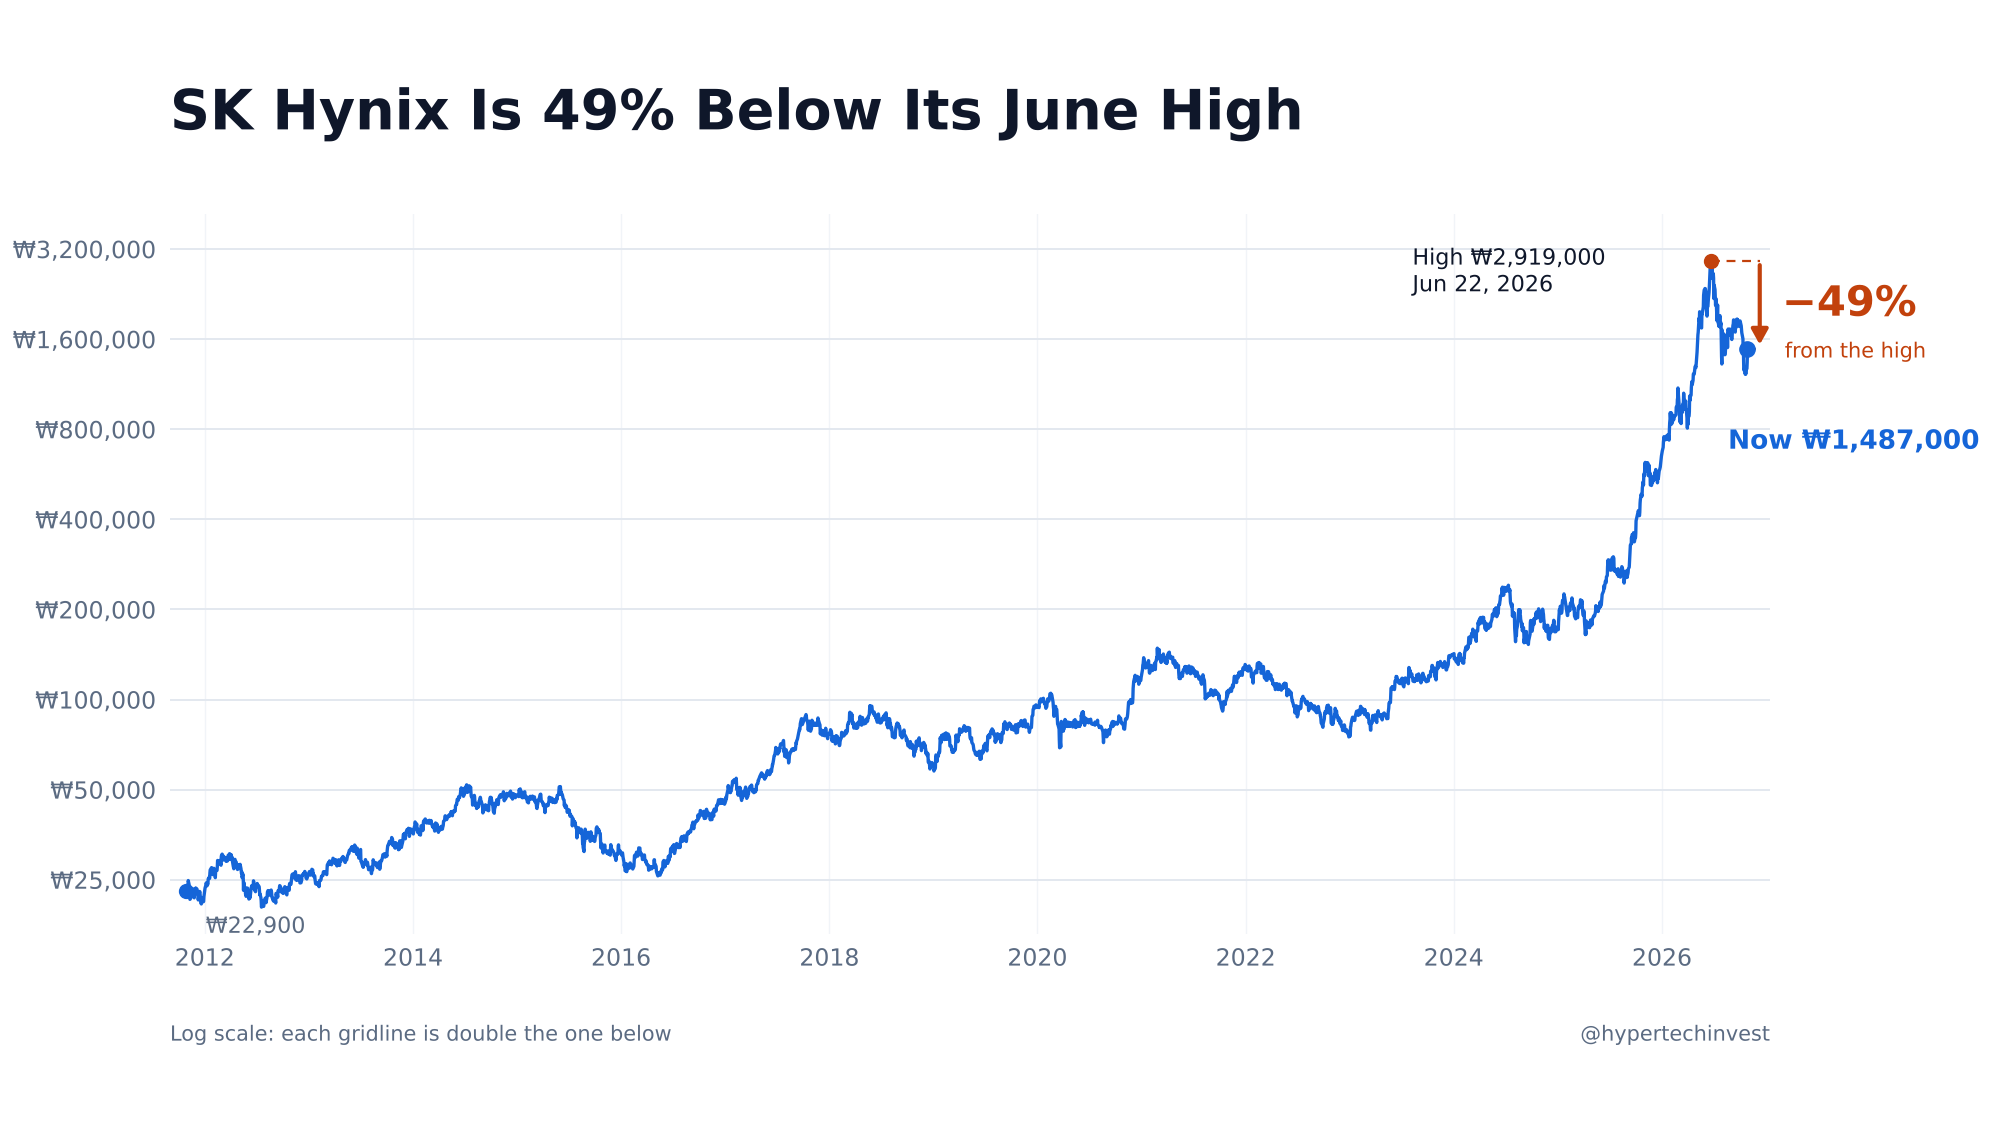
Is this a bargain created by temporary macro headwinds,
or are we actually at a market peak that could turn into a bull trap?
That’s what I’ll be trying to answer today.