

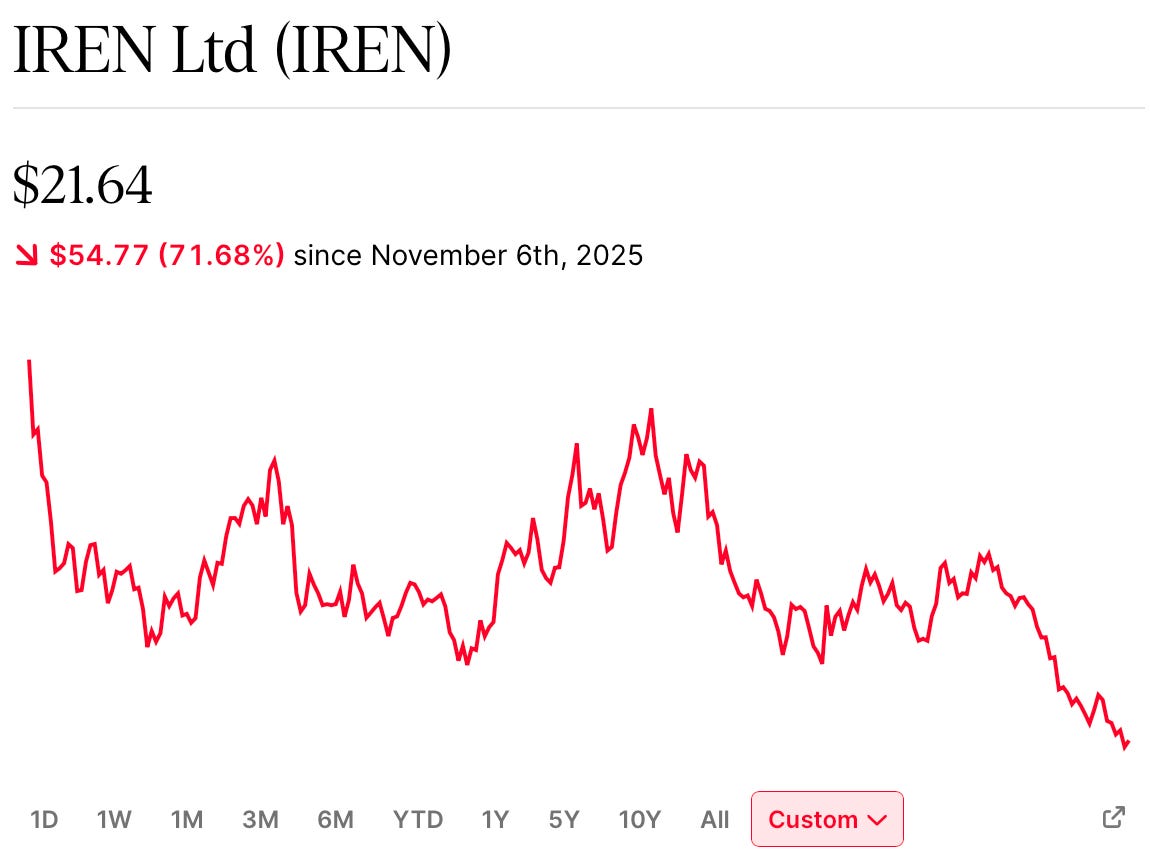
IREN is down 71% from its all-time high, reached on November 6, 2025.
The stock is now trading at levels not seen since August 2025.
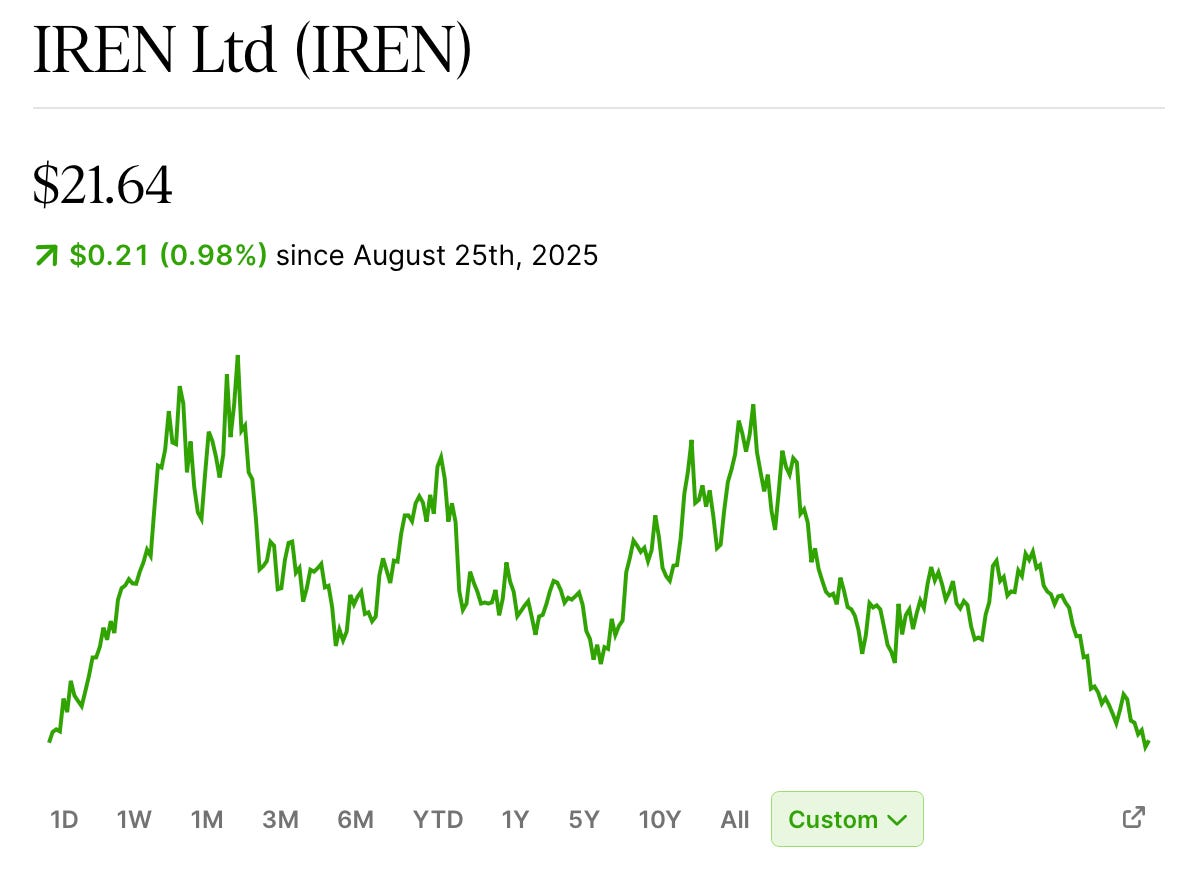
Which is surprising, considering that since August 2025, IREN has:
Grown quarterly AI Cloud revenue 27×, from $7.3M to $200M.
Signed a $9.7B contract with Microsoft and a $3.4B contract with NVIDIA.
Secured an impressive AI Cloud customer base, including Microsoft, NVIDIA, Perplexity, Figure AI, Together AI, Cohere, Fireworks AI, fal.ai, Hume AI, and an undisclosed leading frontier AI lab.
Expanded its contracted revenue backlog to over $20B, with two-thirds backed by investment-grade customers.
Reached $1B in operating AI Cloud ARR, with over $4B in ARR contracted and fully funded for deployment.
Expanded secured power capacity from 2.9 GW to over 5 GW, with another 35 GW in development.
Expanded its land portfolio to over 30,000 acres across three continents.
Delivered its first 50 MW liquid-cooled AI cluster in just 14 months, achieving NVIDIA Exemplar Cloud status.
Accumulated $6B in unencumbered data-center assets, providing significant additional financing flexibility.
Achieved 86% AI Cloud gross margins.
Demonstrated 18-month GPU paybacks and three-year total infrastructure paybacks.
Signed new five-year contracts at $22M per MW annually, with customers prepaying up to 90% of GPU capex.
Secured short-term contracts at annualized pricing exceeding $40M per MW.
Renewed older H100 GPUs at double their previous rental pricing, locking in the higher rates for multiple years.
Strengthened its relationship with NVIDIA, collaborating on next-generation AI data-center design, modular construction, and GPU power optimization.
While it’s true that share dilution explains part of the disconnect between the stock price and the company’s fundamentals, the reality is undeniable: IREN is already experiencing one of the most severe drawdowns in its public-market history.
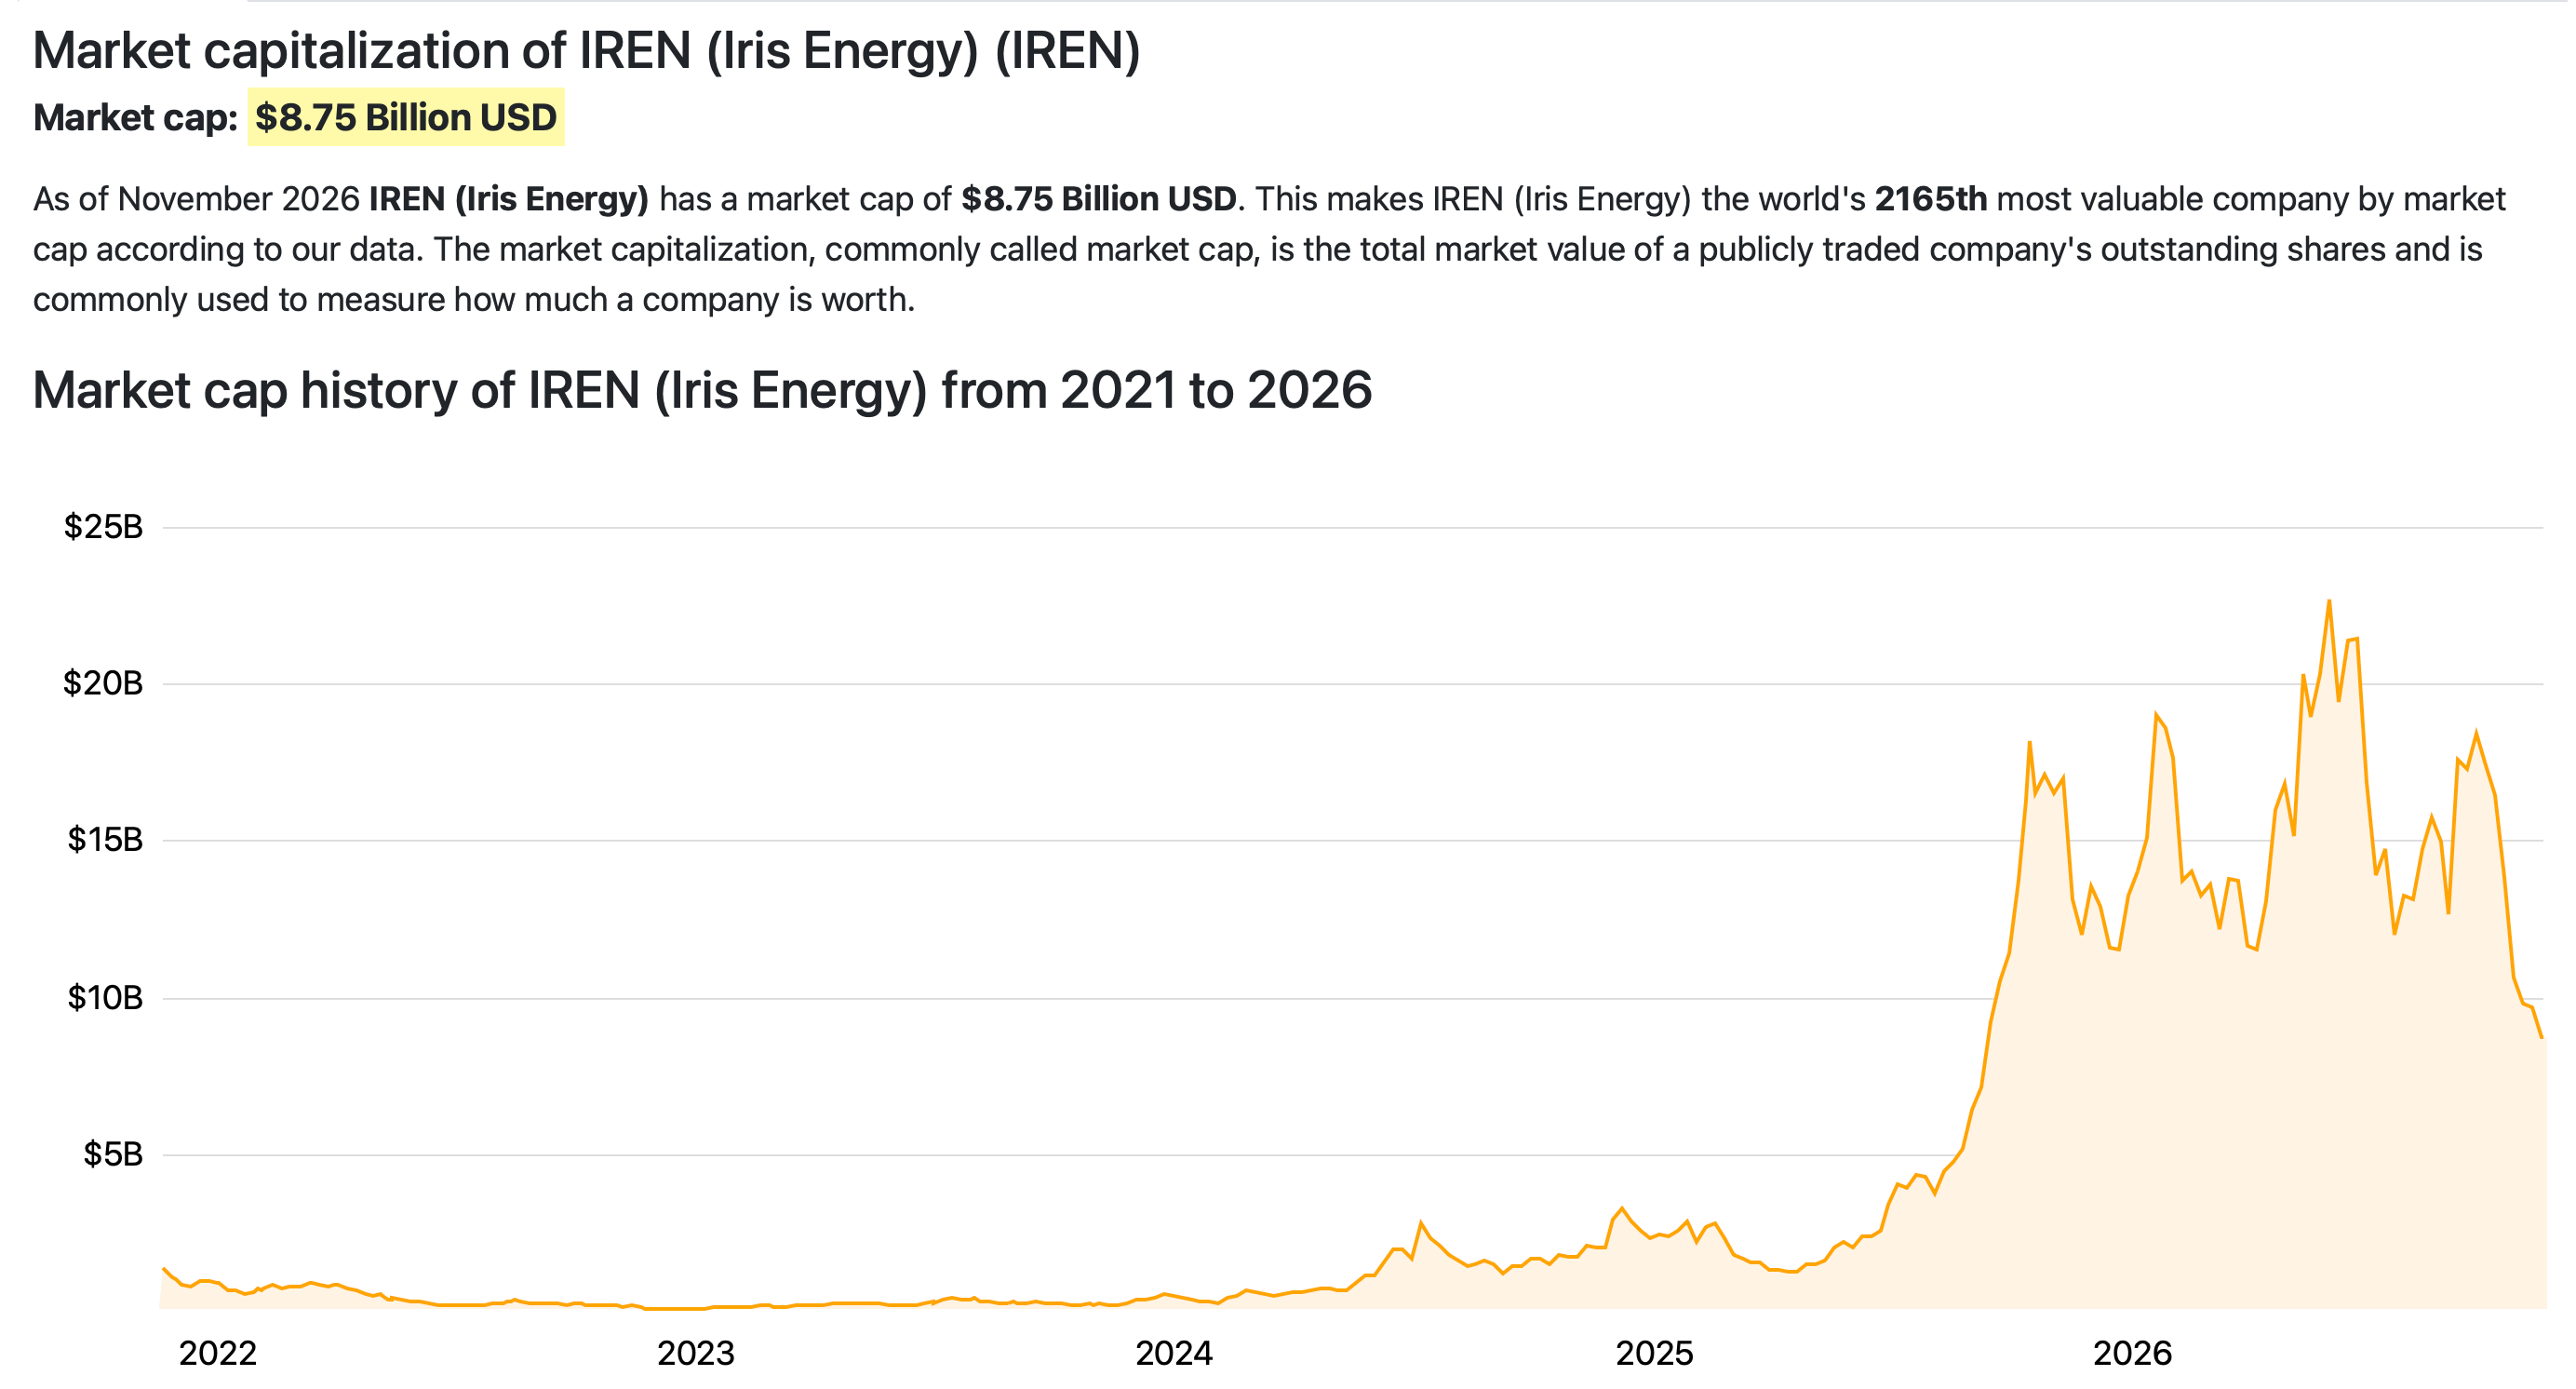
In this article, I’ll review IREN’s latest earnings, address investors’ main concerns, and reassess the investment thesis.
Let’s get started.